The “Goldilocks valuation zone” is best treated as a screening concept, not a fixed rule that tells you which technology company will be acquired. A target becomes “just right” only when the buyer can justify the price through strategic fit, business quality, integration feasibility and acceptable regulatory risk. The useful question is therefore not “Is the company below a certain market cap or sales multiple?” but “Does this price make sense for this buyer and this strategic problem?”
The phrase became popular as a way to describe a middle ground between tiny acquisitions that may not move the needle and enormous transactions that can strain financing, integration and regulatory tolerance. The same strategic tension appears when companies respond to emerging technologies and their implications for the business world: buying speed can be valuable, but only when the acquired capability can be absorbed and scaled. A 2022 version of the screen highlighted roughly $5 billion to $30 billion of market capitalization, a forward price-to-sales ratio below about 10, and disruptive technology potential. Those figures were a market snapshot, not a durable acquisition formula.
| 2022 screen | What it was trying to capture | More durable interpretation |
|---|---|---|
| $5B-$30B market cap | Large enough to matter, but potentially financeable by a large buyer | Deal size must be judged against the buyer’s cash, debt capacity, equity, opportunity cost and tolerance for a transformational transaction. |
| Below ~10x forward P/S | Avoiding the most extreme sales valuations | Use enterprise-value/revenue or another relevant multiple alongside growth, margins, retention, profitability, capital intensity and expected synergies. |
| Disruptive potential | A target that could change a product category or strategic position | Test strategic adjacency, customer access, product differentiation, talent, data, intellectual property and speed-to-market advantages. |
Why there is no universal Big Tech valuation sweet spot
Two targets with the same enterprise value can be radically different acquisitions. One may bring recurring revenue, a sticky installed base and technology that plugs directly into the buyer’s distribution; another may require years of product integration, overlap heavily with existing offerings and create little customer pull. The headline valuation is identical, but the economic burden and strategic payoff are not.
A buyer also has its own constraints. A $20 billion transaction may be manageable for one company and transformational for another, while a smaller target can still be expensive if its revenue quality is weak or the expected synergies depend on heroic assumptions. This is why acquisition valuation needs to be buyer-specific rather than based on a market-cap band alone.
Five factors that make an innovative target more attractive
Strong acquisition logic usually comes from a combination of strategic and operating fit rather than a single cheap multiple. That is especially true when a buyer is evaluating how AI can transform business, because a promising capability still needs distribution, data, workflow integration and a credible path to value. The most useful first pass is to ask whether the target solves a real capability gap, can reach more customers through the buyer, owns something difficult to reproduce, can actually be integrated, and can survive competition and regulatory review.
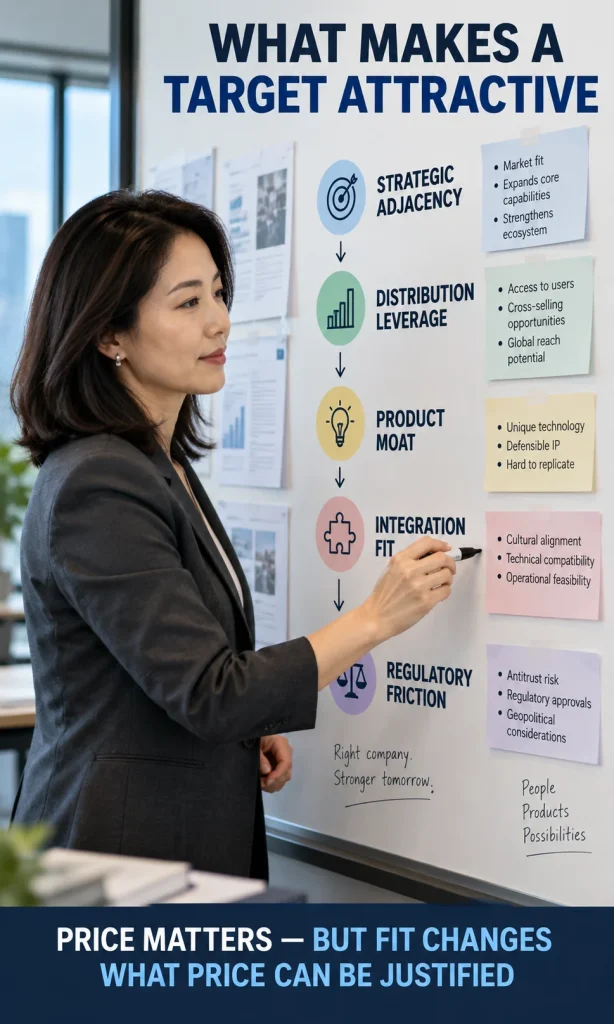
- Strategic adjacency: the target strengthens a product, platform, customer segment or capability the buyer already understands.
- Distribution leverage: the buyer can put the target in front of more customers, regions or channels without destroying the product’s value proposition.
- Defensible capability: technology, data, talent, workflow position, intellectual property or customer relationships would be slower or riskier to build internally.
- Integration feasibility: systems, product architecture, people, incentives and go-to-market motions can be combined without erasing the reason the target was attractive.
- Regulatory friction: competitive overlap, platform effects, data access and market structure do not create a level of delay or remedy risk that overwhelms the deal logic.
Valuation multiple is only one lens
A revenue multiple is useful because it creates a common denominator, especially for software companies whose earnings may be depressed by growth investment. It is still incomplete. A 6x revenue multiple can be demanding for a low-growth, low-retention business, while a higher multiple may be economically defensible when a target has durable growth, strong margins, high retention and synergies that are credible rather than merely aspirational.
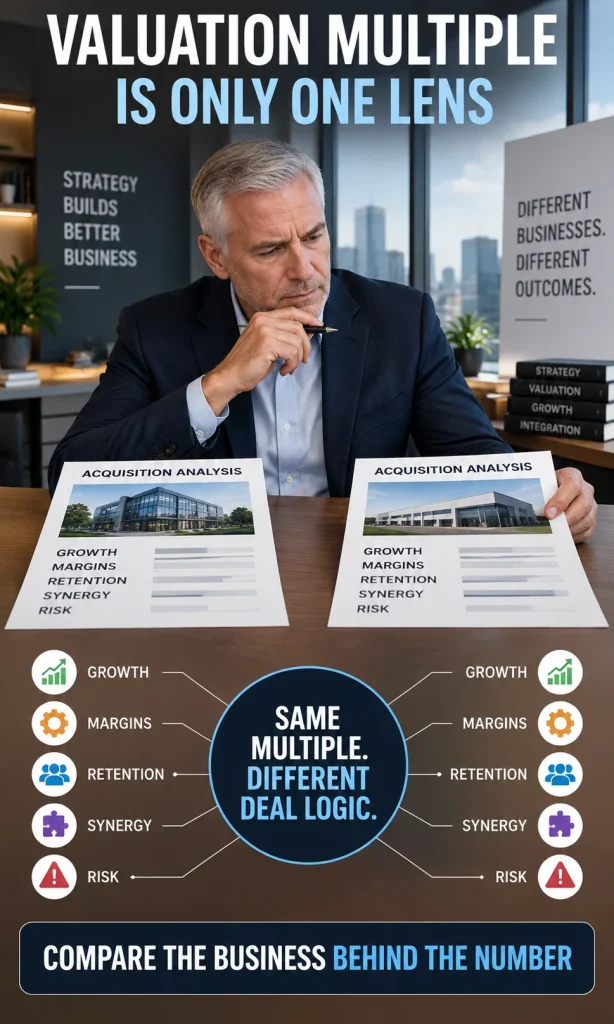
Enterprise value is usually more informative than market capitalization for acquisition analysis because it incorporates debt and cash into the value of the operating business. Even then, the multiple should be interpreted alongside the target’s revenue mix, gross margin, customer concentration, churn, required reinvestment and the buyer’s realistic ability to create value after closing.
Splunk shows why the original screen was a clue, not a law
The old Goldilocks thesis used Splunk as an example of a technology company that had fallen into a more digestible valuation range while retaining strategic value. That did not make an acquisition inevitable, but the strategic logic eventually became real: Cisco completed its acquisition of Splunk for approximately $28 billion in equity value, describing security, observability, data and AI as central parts of the combination.
The more important lesson is not that $28 billion is a magic number. Salesforce’s agreement to buy Slack carried an enterprise value of about $27.7 billion, while Microsoft’s announced Activision Blizzard transaction was $68.7 billion including net cash. Strategic buyers can operate well outside the old range when the target is important enough and the buyer can support the financial, operational and regulatory burden.
Regulatory risk can change the acceptable price
For large platform and technology acquisitions, competition review is part of valuation rather than a separate legal footnote. The U.S. Merger Guidelines describe scrutiny of potential entrants, serial acquisitions, multi-sided platforms and transactions that may entrench a dominant position. In the European Union, gatekeepers also have an obligation under Article 14 of the Digital Markets Act to inform the European Commission about qualifying intended concentrations.
A transaction with major overlap may therefore deserve a lower internal willingness-to-pay than an otherwise similar target with cleaner competitive separation, because delay, remedies, litigation risk and management distraction all have economic value. This does not mean “high regulatory risk equals bad deal”; it means the risk should be priced into timing, structure, integration planning and the probability that the original strategy can still be executed.
Five checks before calling a target a sweet spot
Instead of screening only for a market-cap range, use a sequence that forces the strategic case and the valuation case to agree. A deal should become more convincing as each question is answered, not merely because the target’s share price has fallen.
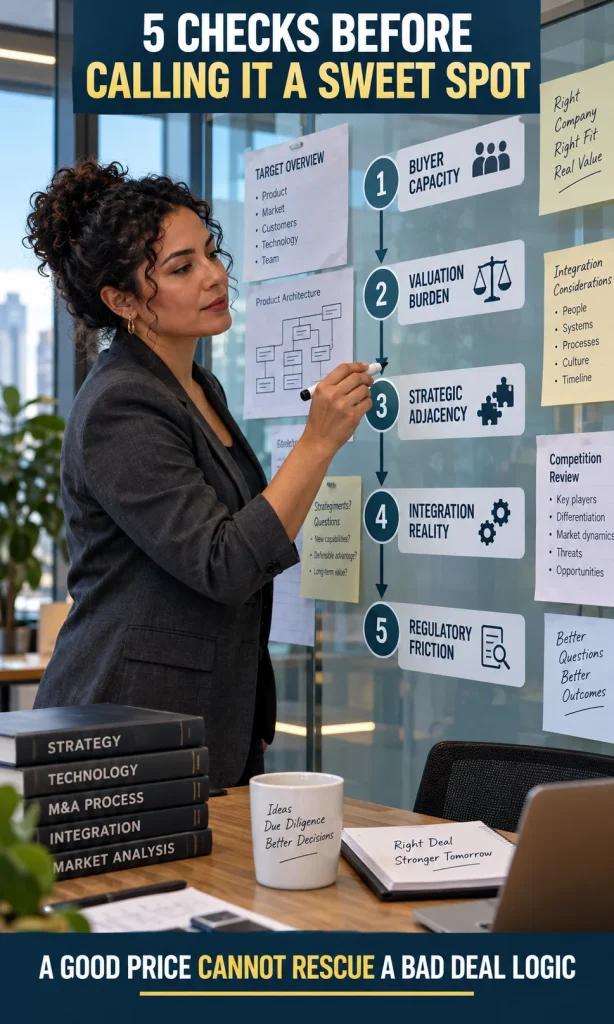
- Buyer capacity: Can the buyer fund the transaction without crowding out more valuable uses of cash, debt capacity or equity?
- Valuation burden: What revenue, margin, cash flow or strategic outcomes are already implied by the price?
- Strategic adjacency: Does the target strengthen a business the buyer can actually accelerate?
- Integration reality: Which products, systems, teams and customer motions must work together for the thesis to succeed?
- Regulatory friction: Could market overlap, platform power, data access or jurisdiction-specific rules materially change the deal?
Use the Acquisition Fit Studio
The interactive experience below does not produce a takeover probability or a “buy” signal. It calculates a simple enterprise-value/revenue multiple, compares it with a reference multiple you choose, and organizes the strategic, integration and regulatory questions that still need diligence.
Acquisition Fit Studio
Test whether a target's price, strategic logic, integration burden and regulatory friction line up.
1. Enter the deal context
2. Read the profile
What to verify next
Common mistakes when looking for acquisition candidates
- Treating a fallen share price as cheapness: a lower price can reflect weaker growth, deteriorating retention or a changed competitive position.
- Using market cap instead of enterprise value: debt and cash can materially change the actual price of the operating business.
- Assuming strategic fit automatically creates synergies: distribution and product combinations need a specific mechanism, not a generic “cross-sell” label.
- Ignoring integration costs: duplicated systems, compensation changes, product migrations and customer uncertainty can consume expected value.
- Ignoring antitrust and platform effects: a strategically attractive target can become harder to buy precisely because it is important to competition.
- Turning a takeover thesis into an investment thesis: an attractive business should not depend on being acquired to justify the investment case.
Frequently Asked Questions
Is $5 billion to $30 billion still the Goldilocks valuation zone for Big Tech?
No. That range was a historical screening idea, not a universal or current rule. Deal size has to be judged against the buyer’s resources, the target’s business quality, the strategic thesis, integration complexity and regulatory risk.
Is a lower price-to-sales or EV-to-revenue multiple always better?
No. A lower multiple can reflect slower growth, weak retention, low margins or higher business risk. The multiple needs context from revenue quality, profitability, customer economics, capital intensity and the buyer’s credible synergy plan.
Why use enterprise value instead of market capitalization for an acquisition?
Enterprise value better approximates the value of the operating business because it adjusts equity value for debt and cash. The exact transaction price can still differ because of premiums, assumed liabilities, financing structure and negotiated terms.
Does a strong strategic fit mean regulators will approve a technology acquisition?
No. Strategic logic for the buyer and competition analysis are different questions. Regulators may examine market concentration, potential competition, platform effects, data, inputs, serial acquisitions and other jurisdiction-specific issues.
Should investors buy a company because it looks like an acquisition target?
A takeover possibility should not substitute for an investment thesis. Acquisition timing, buyer interest, price and regulatory clearance are uncertain, so the standalone business still needs to make sense on its own merits and risks.
The useful version of the Goldilocks idea
The durable insight is that strategic acquisitions sit at the intersection of affordability and consequence. A target has to be important enough to improve the buyer’s position, priced so the economics can work, integrable enough to preserve the expected value, and clear enough that the transaction can realistically be completed. That is a moving zone defined by the buyer and the target – not a permanent market-cap band.